Business Insights
  • Home
  • Crypto
  • Finance Expert
  • Business
  • Invest News
  • Investing
  • Trading
  • Forex
  • Videos
  • Economy
  • Tech
  • Contact

Archives

  • October 2026
  • September 2026
  • August 2026
  • July 2026
  • June 2026
  • May 2026
  • April 2026
  • March 2026
  • February 2026
  • January 2026
  • December 2025
  • November 2025
  • October 2025
  • September 2025
  • August 2025
  • July 2025
  • June 2025
  • May 2025
  • April 2025
  • March 2025
  • February 2025
  • January 2025
  • December 2024
  • November 2024
  • October 2024
  • September 2024
  • August 2024
  • July 2024
  • June 2024
  • May 2024
  • April 2024
  • March 2024
  • February 2024
  • August 2023
  • January 2023
  • December 2021
  • July 2021
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019

Categories

  • Business
  • Crypto
  • Economy
  • Finance Expert
  • Forex
  • Invest News
  • Investing
  • Tech
  • Trading
  • Uncategorized
  • Videos
Apply Loan
Money Visa
Advertise Us
Money Visa
  • Home
  • Crypto
  • Finance Expert
  • Business
  • Invest News
  • Investing
  • Trading
  • Forex
  • Videos
  • Economy
  • Tech
  • Contact
The Real Down Payment: Here’s How Much You’ll Really Need to Put Down On That House
  • Invest News

The Real Down Payment: Here’s How Much You’ll Really Need to Put Down On That House

  • April 7, 2025
  • Roubens Andy King
Total
0
Shares
0
0
0
Total
0
Shares
Share 0
Tweet 0
Pin it 0

The Real Down Payment: Here’s How Much You’ll Really Need to Put Down On That House
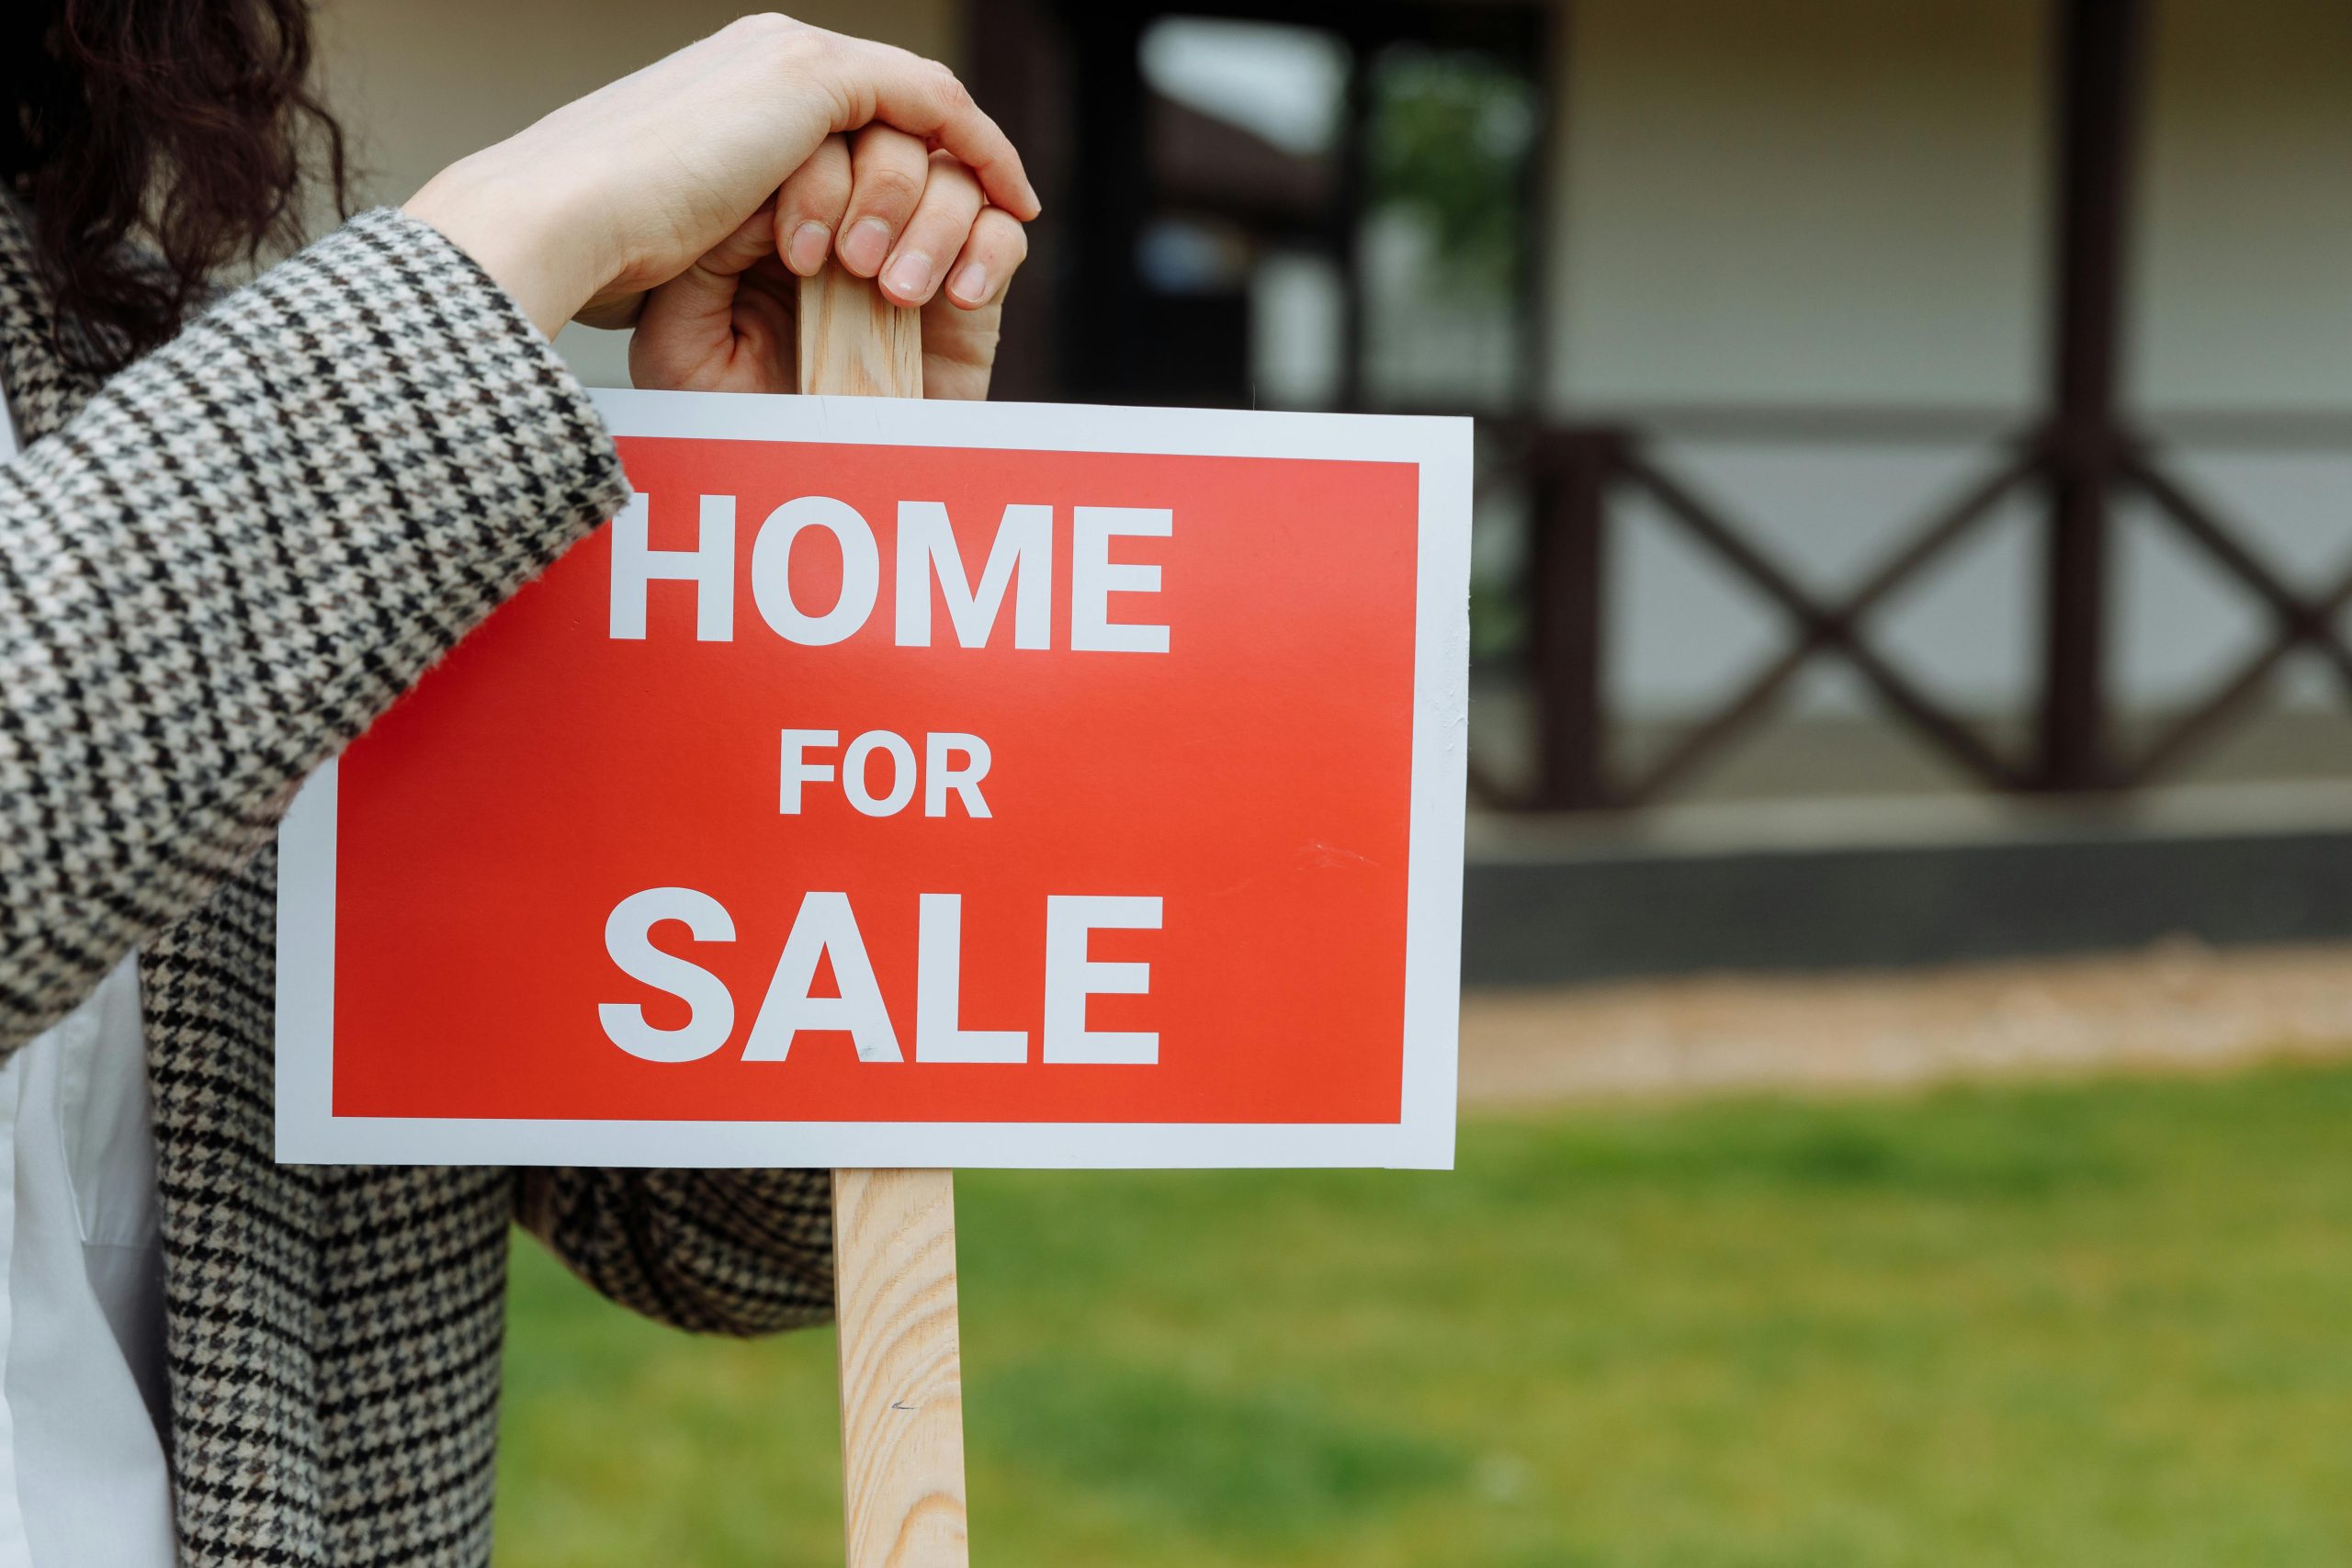
Image by Thirdman of Pexels

When most people think about buying a home, the first big question tends to be: “How much do I need to put down?” You’ve probably heard the old-school rule of thumb—20% down or nothing. That number sounds daunting, especially with today’s home prices. But here’s the good news: the real down payment might be less than you think.

Let’s break down what you truly need to know—because buying a home isn’t just about scraping together a pile of cash. It’s about understanding your options, preparing for hidden costs, and creating a plan that doesn’t wreck your finances before you even move in.

The 20% Myth and Where It Came From

For decades, a 20% down payment was considered the “standard.” Not because it was required but because it helped buyers avoid private mortgage insurance (PMI), a monthly fee added to protect the lender when buyers put down less money. While avoiding PMI is a nice bonus, it’s not a requirement. In fact, most Americans don’t pay 20% upfront when buying their first home.

According to the National Association of Realtors, first-time buyers typically put down just 6% to 8%. For repeat buyers, the average is around 13%—still well below the traditional 20%. What does this mean for you? Simply put, you have options.

What Determines How Much You Have to Put Down?

The amount you’ll need varies depending on several key factors, especially the type of mortgage you choose. A conventional loan, which isn’t backed by the government, usually offers options as low as 3% for first-time buyers. FHA loans, popular among buyers with moderate credit or income, require 3.5%. And if you’re eligible for VA or USDA loans—designed for veterans and rural areas—you might qualify for a mortgage with zero down.

Each loan type comes with its own rules, and your credit score, debt-to-income ratio, and even your location can influence how much your lender asks you to contribute upfront. What’s important is that you don’t assume 20% is your only path forward. Plenty of buyers get the keys to their first home with far less in the bank.

What Else Do You Need Besides a Down Payment?

This is where many first-time buyers get caught off guard. You’ve saved for a down payment—maybe 5% or even 10%—and you’re ready to go. But then your lender mentions something called “closing costs,” and suddenly, the finish line seems farther away.

Closing costs typically add another 2% to 5% of the purchase price to your upfront expenses. These cover things like title insurance, loan origination fees, taxes, and legal filings. And while some of these fees can occasionally be negotiated or covered by the seller, it’s best to plan as if you’ll be responsible for all of them.

Add to that a home inspection (which, while optional, is highly recommended), an appraisal, moving expenses, and any immediate repairs or upgrades your new home might need. It’s not unusual for buyers to need an additional $8,000 to $15,000 on top of their down payment.

Real-Life Example: What Does That Look Like?

Let’s say you’re eyeing a $350,000 home. You plan to put down 5%, which is $17,500. That sounds manageable, right? But when you factor in estimated closing costs at 3%—around $10,500—your total cash needed at closing climbs to roughly $28,000. And that doesn’t include moving trucks, utility deposits, or the new couch you’ll probably want to buy.

This number isn’t meant to scare you off; it’s meant to empower you. When you understand the full cost of buying a home, you can plan smarter and avoid surprises.

Are There Ways to Reduce That Number?

Absolutely. Many buyers, especially first-timers, qualify for down payment assistance programs through their state or local housing authorities. These programs can offer grants, forgivable loans, or matched savings programs that can help cover some or all of your upfront costs.

You can also use gifted funds from a family member to help with your down payment, though most lenders require documentation to show the money is truly a gift and not a loan. Be prepared to provide a gift letter and proof of the transfer.

Some buyers also work with lenders who offer “lender credits,” which reduce your closing costs in exchange for a slightly higher interest rate. This can make sense if you're short on upfront cash but plan to refinance or sell in the near future.

How Much Should You Put Down?

There’s no one-size-fits-all answer. Some buyers want the lowest possible monthly payment and peace of mind from avoiding PMI, so they wait until they’ve saved 20% or more. Others are eager to buy now, build equity, and refinance later. What matters most is your financial stability.

If putting down a larger amount would leave you without an emergency fund, delay necessary repairs, or put your overall financial well-being at risk, it might not be worth it. You can always pay more later, but you can’t undo a financial stretch that leaves you living house-poor.

The Bottom Line

Buying a home is a major milestone, and your down payment is a big part of that journey. But it doesn’t have to be a barrier. Whether you put down 3%, 10%, or more, what’s most important is understanding the full picture and knowing that help is available.

Start by exploring loan options, researching local assistance programs, and getting pre-approved to see what you qualify for. Build a plan that fits your financial reality, not outdated advice. Because the real down payment isn’t just what you can afford—it’s what you can sustain comfortably for the long term.

Do you think that this is a reasonable percentage with the house prices these days?

Read More:

Buying a Home? These Simple Savings Hacks Will Get You There Faster!

The Best Loopholes for Buying a Home
Source link

Total
0
Shares
Share 0
Tweet 0
Pin it 0
Roubens Andy King

Previous Article
How Well Did Tariffs Work in Trump’s First Term? #finance #tariff #economy #tariffs #tariffimpact
  • Videos

How Well Did Tariffs Work in Trump’s First Term? #finance #tariff #economy #tariffs #tariffimpact

  • April 7, 2025
  • Roubens Andy King
Read More
Next Article
9 Cities That Were Once Thriving, Now Barely Recognizable
  • Invest News

9 Cities That Were Once Thriving, Now Barely Recognizable

  • April 7, 2025
  • Roubens Andy King
Read More
You May Also Like
Scott Speedman Says Beau Bridges’ R.J. Decker Story ‘Isn’t Over Yet’ as His Love Triangle Gets Messier
Read More
  • Invest News

Scott Speedman Says Beau Bridges’ R.J. Decker Story ‘Isn’t Over Yet’ as His Love Triangle Gets Messier

  • Roubens Andy King
  • October 7, 2026
Unemployed Husbands Had 138% Higher Odds of Divorce 2 Years Later, Study Finds
Read More
  • Invest News

Unemployed Husbands Had 138% Higher Odds of Divorce 2 Years Later, Study Finds

  • Roubens Andy King
  • October 3, 2026
Robert Pattinson Finally Picks His Favorite Meme of Himself, but He Still Has No Idea Why It’s Funny
Read More
  • Invest News

Robert Pattinson Finally Picks His Favorite Meme of Himself, but He Still Has No Idea Why It’s Funny

  • Roubens Andy King
  • September 27, 2026
What Happens If Nobody Claims a Life Insurance Policy?
Read More
  • Invest News

What Happens If Nobody Claims a Life Insurance Policy?

  • Roubens Andy King
  • September 23, 2026
Make money by selling your hair
Read More
  • Invest News

Make money by selling your hair

  • Roubens Andy King
  • September 23, 2026
Which Is Right for You?
Read More
  • Invest News

Which Is Right for You?

  • Roubens Andy King
  • September 20, 2026
Fed Breaks Three-Year Pause, Raises Rates a Quarter Point as Inflation Refuses to Cool
Read More
  • Invest News

Fed Breaks Three-Year Pause, Raises Rates a Quarter Point as Inflation Refuses to Cool

  • Roubens Andy King
  • September 17, 2026
Kendall Jenner Denies Dating Cara Delevingne, Then Jokes ‘Never Say Never’
Read More
  • Invest News

Kendall Jenner Denies Dating Cara Delevingne, Then Jokes ‘Never Say Never’

  • Roubens Andy King
  • September 17, 2026

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Recent Posts

  • குடும்பத் தலைவிகளுக்கு நல்ல ஐடியா👌🏻 | குறைந்த முதலீட்டில் தொழில் தொடங்க Business Ideas🔥 | Low budget
  • Federal Reserve Board – Federal Reserve Board releases results of the 2025 Survey of Consumer Finances, which provides the public and policymakers with detailed insights into the economic condition of American families
  • SPENT $17,000 ON A $4,000 SALARY?! #calebhammer #podcast #finance #financialaudit #podcast
  • Federal Reserve Board – Federal Reserve Board announces enforcement action against American Express Company to address, among other things, the firm’s failure to sufficiently detect and report certain suspicious activity related to money laundering
  • risk of shortages ruled out for the time being, but increased risk of price rises
Featured Posts
  • குடும்பத் தலைவிகளுக்கு நல்ல ஐடியா👌🏻 | குறைந்த முதலீட்டில் தொழில் தொடங்க Business Ideas🔥 | Low budget 1
    குடும்பத் தலைவிகளுக்கு நல்ல ஐடியா👌🏻 | குறைந்த முதலீட்டில் தொழில் தொடங்க Business Ideas🔥 | Low budget
    • October 9, 2026
  • Federal Reserve Board – Federal Reserve Board releases results of the 2025 Survey of Consumer Finances, which provides the public and policymakers with detailed insights into the economic condition of American families 2
    Federal Reserve Board – Federal Reserve Board releases results of the 2025 Survey of Consumer Finances, which provides the public and policymakers with detailed insights into the economic condition of American families
    • October 9, 2026
  • SPENT ,000 ON A ,000 SALARY?! #calebhammer #podcast #finance #financialaudit #podcast 3
    SPENT $17,000 ON A $4,000 SALARY?! #calebhammer #podcast #finance #financialaudit #podcast
    • October 8, 2026
  • Federal Reserve Board – Federal Reserve Board announces enforcement action against American Express Company to address, among other things, the firm’s failure to sufficiently detect and report certain suspicious activity related to money laundering 4
    Federal Reserve Board – Federal Reserve Board announces enforcement action against American Express Company to address, among other things, the firm’s failure to sufficiently detect and report certain suspicious activity related to money laundering
    • October 8, 2026
  • risk of shortages ruled out for the time being, but increased risk of price rises 5
    risk of shortages ruled out for the time being, but increased risk of price rises
    • October 8, 2026
Recent Posts
  • double-digit growth in business creations, a slowdown in the rise in bankruptcies and stable non-performing loans ratio
    double-digit growth in business creations, a slowdown in the rise in bankruptcies and stable non-performing loans ratio
    • October 8, 2026
  • Top Stocks I’m Buying For Massive Growth In April 2026
    Top Stocks I’m Buying For Massive Growth In April 2026
    • October 7, 2026
  • Scott Speedman Says Beau Bridges’ R.J. Decker Story ‘Isn’t Over Yet’ as His Love Triangle Gets Messier
    Scott Speedman Says Beau Bridges’ R.J. Decker Story ‘Isn’t Over Yet’ as His Love Triangle Gets Messier
    • October 7, 2026
Categories
  • Business (2,057)
  • Crypto (2,023)
  • Economy (357)
  • Finance Expert (1,687)
  • Forex (2,016)
  • Invest News (2,523)
  • Investing (2,040)
  • Tech (2,056)
  • Trading (2,024)
  • Uncategorized (2)
  • Videos (1,184)

Subscribe

Subscribe now to our newsletter

Money Visa
  • Privacy Policy
  • DMCA
  • Terms of Use
Money & Invest Advices

Input your search keywords and press Enter.