
.
We own real assets for their diversification benefits generally, and for their inflation-hedging properties specifically.
Real assets’ first test in modern times started in 2021, when inflation climbed to levels not seen in more than a generation, taking more than two years to subside.
A practitioner might ask, “Did real assets perform as hoped during this episode?”
While dispersion among manager returns is undoubtedly high, broad-market, real-asset index data suggests that real assets failed to hedge the 2021 to 2023 inflation episode.
In this blog, I review the performance of three indexes representative of asset classes that an allocator might include in a real-asset bucket: the S&P Global Infrastructure Index (SPGI), the S&P Natural Resources Index (SNRU), the Northern Trust Global Real Estate index (NTGRE), the multi asset Northern Trust Real Assets Allocation (NTRAA), and S&P Real Assets Indexes (SP_REAL). I use the period of surging inflation that began in 2021 and ended in 2023.
For comparison, I include the Bloomberg TIPS (BBUTISTR, which I abbreviate “TIPS”), the Bloomberg Commodity total return (BCTR), and the S&P 500 (SPXTR) indexes. My measure of inflation is the consumer price index (CPI) and variables based on it, defined below. Returns and level changes are monthly unless otherwise noted. R code and additional results can be found in an online R Markdown file.
What an Inflation Hedge Should Do
Most investors probably expect to be compensated for the drag that an inflation hedge might impose on a portfolio relative to equities in the form of a return that at least keeps up with changes in the price level.
Asset allocators typically hold potential inflation hedges to a more lenient standard. We ask merely that a hedge exhibit positive correlation with inflation. That is, when the price level rises, so should an inflation hedge.
By either standard, real assets faltered during the recent inflation episode.
Real Assets and COVID-Era Inflation
Exhibit 1 makes my main point. It shows the change in headline CPI inflation on the horizontal axis versus the multi-asset Northern Trust Real Assets Allocation index[1] (on the vertical) for COVID-era inflation, which I define as January 2021 to December 2023.
The correlation is near zero and in fact slightly negative (-0.04), as the ordinary least squares (OLS) best-fit line emphasizes. Results are the same for the S&P Real Assets index. Of course, these results aren’t significant — the sample size (36) is small.
But it’s the actual values, not hypothesis testing, that are of interest. The returns of broad, real-assets benchmarks did not move in the same direction as inflation from 2021 to 2023.
Exhibit 1. Headline CPI and a broad, real-asset benchmark index were uncorrelated during the COVID-era inflation.

Sources: FRED, YCharts, Author’s calculations
Table 1 is a correlation table. It shows that during the COVID-era inflation period, real-asset index returns were negatively associated with headline CPI inflation (third row), as were TIPS and equities. Real assets moved in the wrong direction, on average, in response to changes in inflation.
Also shown in Table 1 are measures of underlying inflation: median and (16%) trimmed mean CPI as calculated by the Federal Reserve Bank of Cleveland. These proxy for persistent inflation, generally associated with a rising output gap or inflation expectations (as captured in the modern-macro Phillips curve). Because they filter out supply shocks from various sources, they are measures of trend inflation (Ball and Mazumder, 2008). And I include traditional core, or ex. food and energy inflation, another measure of inflation’s trend or underlying tendency.
By any of these definitions of trend inflation, real assets were even less of an underlying-inflation hedge than a headline-inflation hedge during the 2021 to 2023 inflation episode.
Table 1. Select asset-class and inflation-measure correlation from 2021 to 2023 (n = 36).
| NTRAA | SP_REAL | SPGI | SNRU | TIPS | BCTR | NTGRE | SPXTR | |
| median_cpi | -0.3 | -0.34 | -0.17 | -0.21 | -0.35 | -0.3 | -0.35 | -0.33 |
| trimmed_mean_cpi | -0.2 | -0.23 | -0.11 | -0.11 | -0.26 | -0.11 | -0.23 | -0.28 |
| cpi | -0.03 | -0.07 | -0.01 | -0.02 | -0.17 | 0.03 | -0.04 | -0.09 |
| core_cpi | -0.17 | -0.15 | -0.14 | -0.16 | -0.08 | -0.09 | -0.14 | -0.17 |
| headline_shock | 0.11 | 0.09 | 0.06 | 0.08 | -0.01 | 0.17 | 0.12 | 0.06 |
Sources: FRED, YCharts, S&P Global, Author’s calculations
Finally, I define headline shocks in the usual, modern-macro way: the difference between headline and underlying inflation, where the proxy for underlying inflation is median CPI. The result is a variable that shows episodes of supply shock inflation and disinflation, as shown in Exhibit 2.
Exhibit 2. Headline shocks can be positive as in 1990 and the early 2020s and unfavorable, or negative and favorable, as in the mid-1980s.

Sources FRED, Author’s calculations
Real assets respond slightly better (positively) to headline shocks than to underlying inflation — the coefficients for real assets variables are generally higher than those for the broad equity market (SPXTR and TIPS). Expanding our sample to the longest common period (2016 to 2024, n = 108), reinforces these conclusions (Table 2).
Table 2. Select asset-class and inflation-measure correlation for longest common period (12/2015-12/2024, n = 109).

Sources: FRED, YCharts, S&P Global, Author’s calculations
Using this longer data set, I can calculate inflation betas in the traditional way, by regressing returns on CPI inflation (using OLS). These betas are insignificant, both statistically and economically, as shown in Table 3. Results from regressions on median CPI are worse for real assets: coefficients are of the wrong sign, smaller (more negative), and estimated with greater certainty as shown in the online supplement.
Table 3. Inflation beta estimates and their uncertainty (n = 109).

* R-squared is zero in each case.
Sources: FRED, YCharts, S&P Global, Author’s calculations
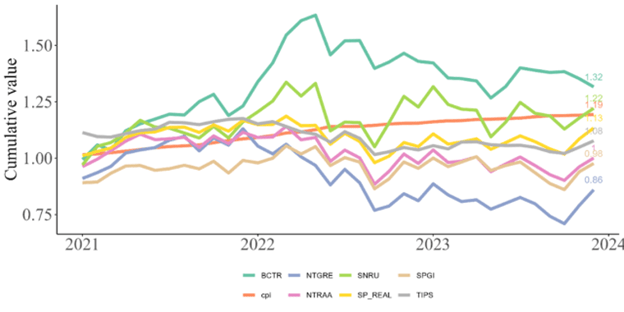
An investor is probably less concerned with correlations and betas than with actual out- (or under-) performance of real assets during an inflation episode. Here the story is also a discouraging one for those expecting inflation protection from real asset classes during the COVID inflation period. As shown in Chart 3, among real assets, only natural resources (SNRU, the light-green line) grew by more, cumulatively, than CPI inflation (the orange line), but only just barely. Among the broader set of indexes considered, only commodities “beat” inflation.
Exhibit 3. Cumulative growth, 2021-2023.
Sources: YCharts, S&P Global, Author’s calculations
The Failure of Real Assets
At least since the 2000s, real assets and inflation-protection strategies have been a fixture of sophisticated asset pools. After decades of dormancy, high inflation resurfaced in 2021. Institutional investors probably felt prepared. But they may have instead been disappointed.
Debate rages among economists whether COVID inflation was the result of supply shocks, demand shocks, or both (see for example Bernanke and Blanchard, 2023, and Giannone and Primiceri, 2024). The “truth” may take years to uncover.
To the degree that the indexes used in this article are representative of manager returns and future behavior of real assets during inflation surges, however, asset allocators can draw conclusions now. When inflation arrived, real assets failed.
References
Ball, L.M. and Mazumder, S. (2019), “The Nonpuzzling Behavior of Median Inflation”, NBER Working Papers, No 25512
Bernanke, B. and Blanchard, O. (2023), “What Caused the US Pandemic-Era Inflation?”, NBER Working Papers, No 31417.
Giannone, D. and Primiceri, G. (2024), “The Drivers of Post Pandemic Inflation”, NBER Working Papers, No 32859
[1] https://www.northerntrust.com/united-states/what-we-do/investment-management/index-services/index-performance/equity/real-assets-allocation-index