Business Insights
  • Home
  • Crypto
  • Finance Expert
  • Business
  • Invest News
  • Investing
  • Trading
  • Forex
  • Videos
  • Economy
  • Tech
  • Contact

Archives

  • September 2026
  • August 2026
  • July 2026
  • June 2026
  • May 2026
  • April 2026
  • March 2026
  • February 2026
  • January 2026
  • December 2025
  • November 2025
  • October 2025
  • September 2025
  • August 2025
  • July 2025
  • June 2025
  • May 2025
  • April 2025
  • March 2025
  • February 2025
  • January 2025
  • December 2024
  • November 2024
  • October 2024
  • September 2024
  • August 2024
  • July 2024
  • June 2024
  • May 2024
  • April 2024
  • March 2024
  • February 2024
  • August 2023
  • January 2023
  • December 2021
  • July 2021
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019

Categories

  • Business
  • Crypto
  • Economy
  • Finance Expert
  • Forex
  • Invest News
  • Investing
  • Tech
  • Trading
  • Uncategorized
  • Videos
Apply Loan
Money Visa
Advertise Us
Money Visa
  • Home
  • Crypto
  • Finance Expert
  • Business
  • Invest News
  • Investing
  • Trading
  • Forex
  • Videos
  • Economy
  • Tech
  • Contact
5 Credit Cards That No One Should Have In Their Wallet
  • Invest News

5 Credit Cards That No One Should Have In Their Wallet

  • April 15, 2025
  • Roubens Andy King
Total
0
Shares
0
0
0
Total
0
Shares
Share 0
Tweet 0
Pin it 0

5 Credit Cards That No One Should Have In Their Wallet
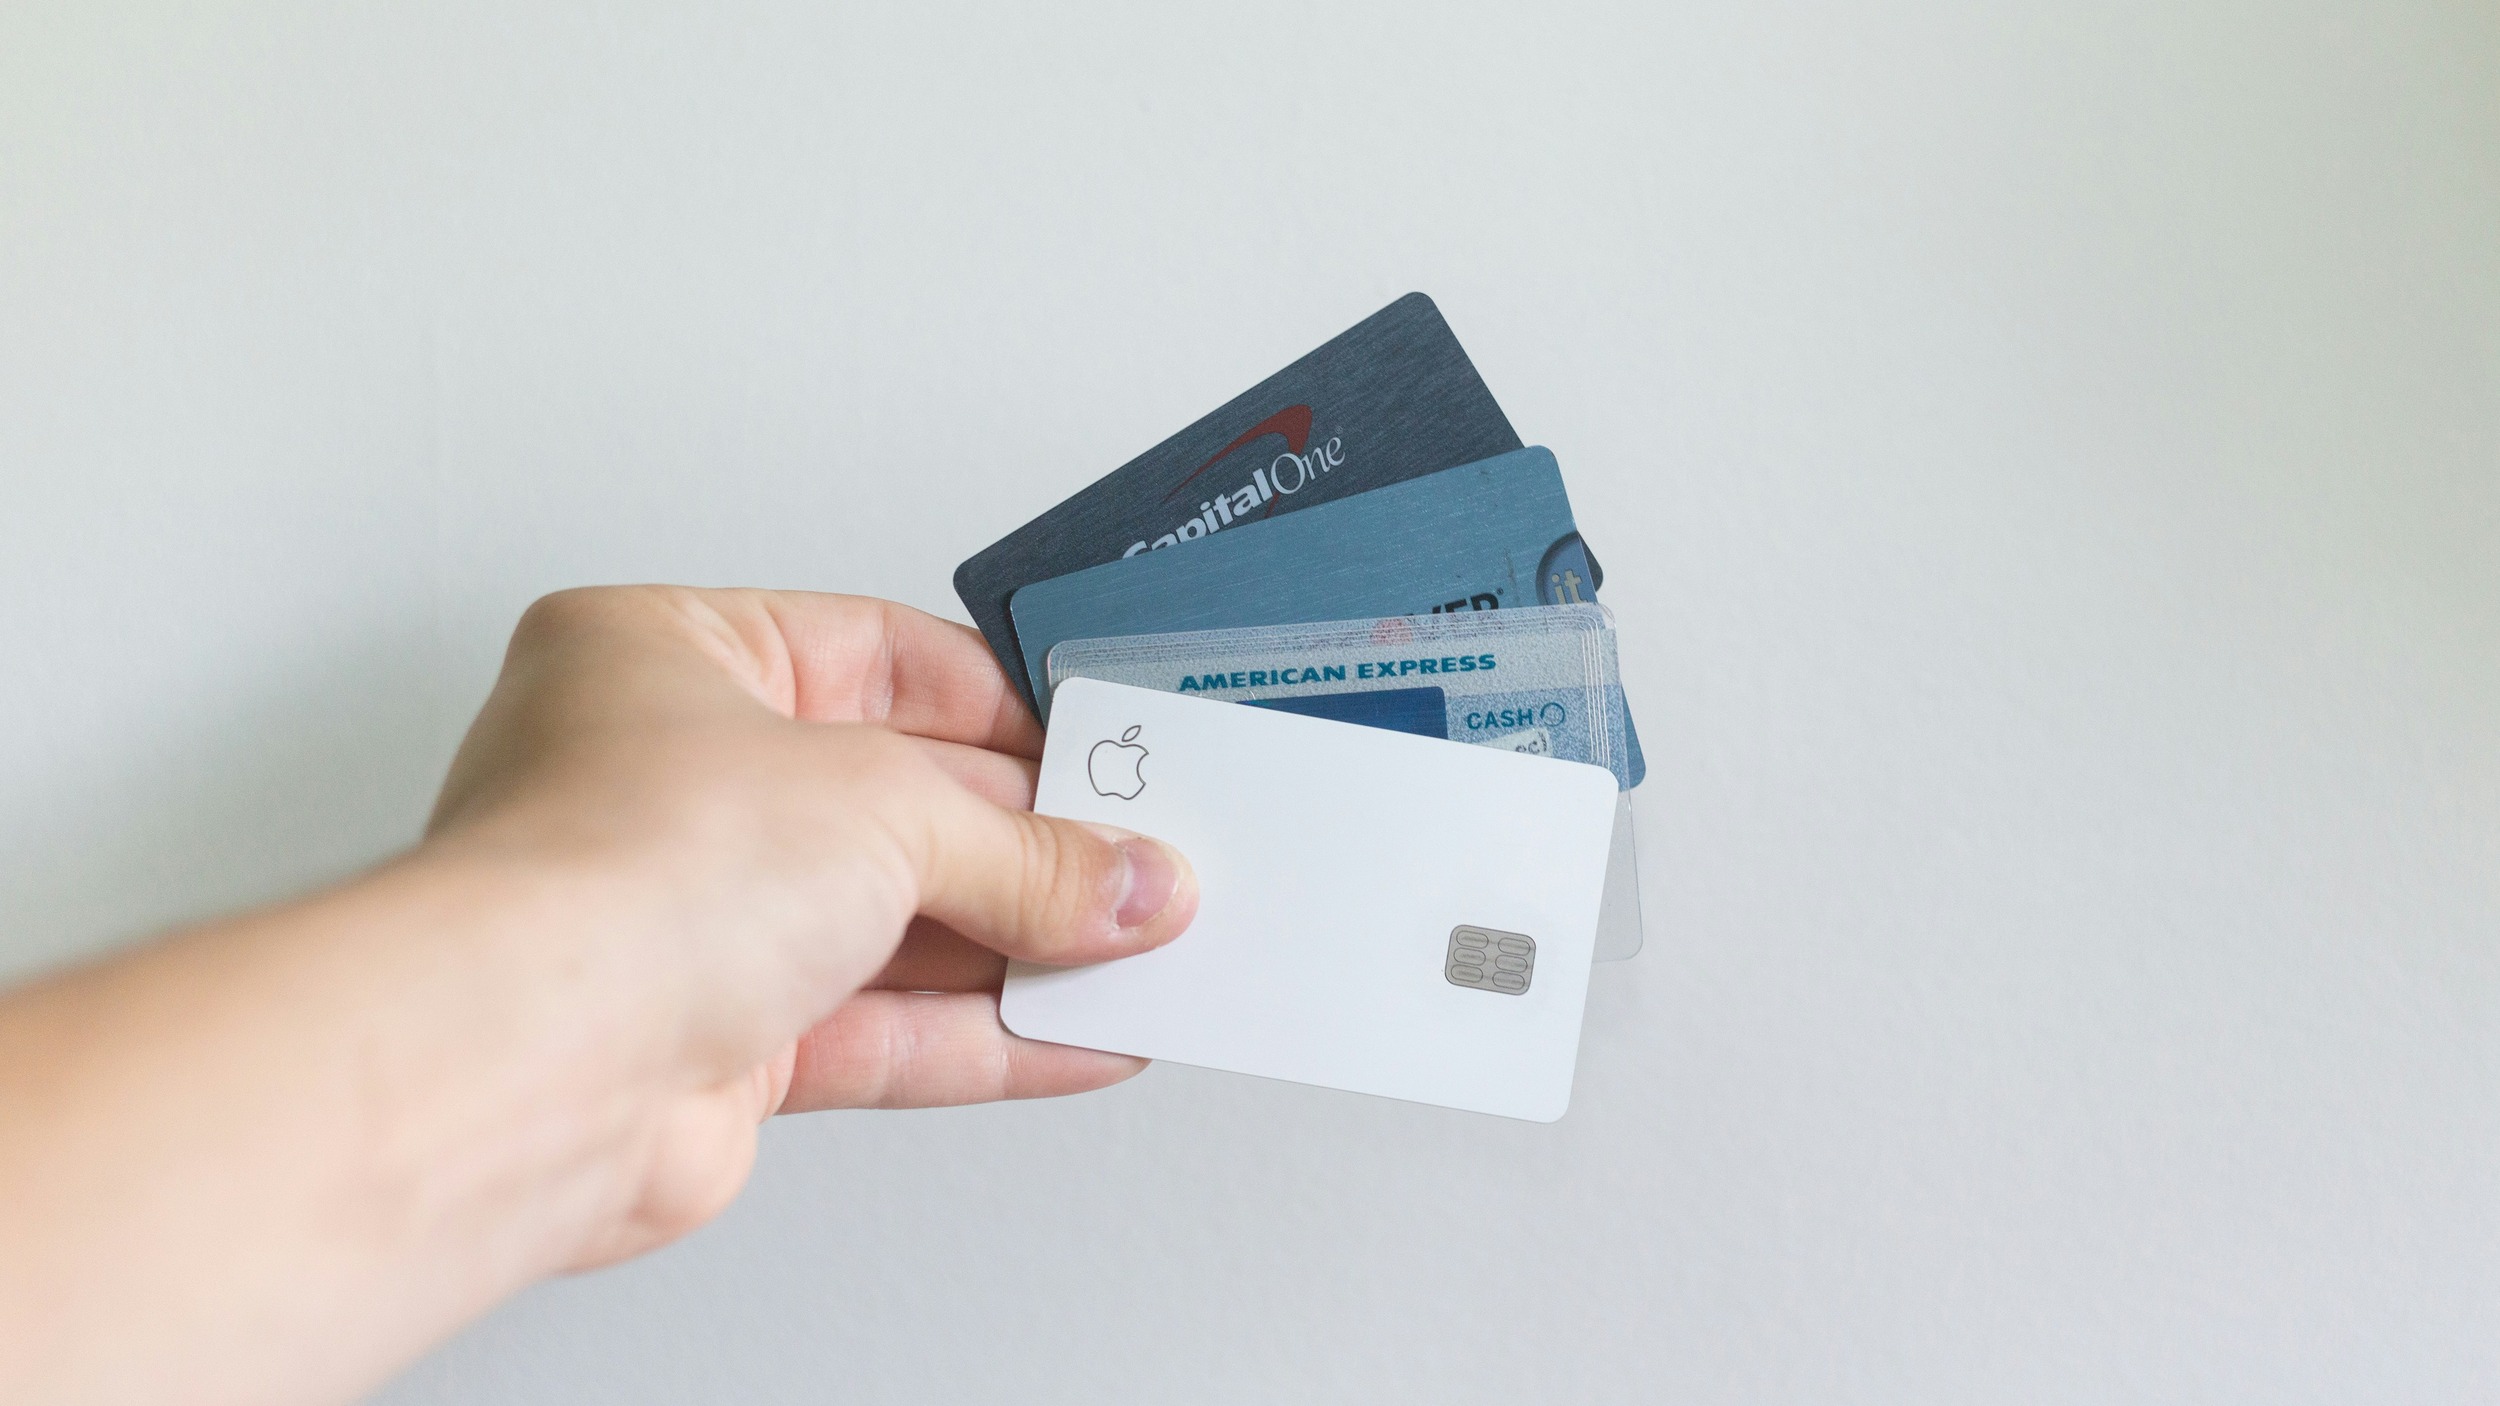
Image by Avery Evans of Unsplash

Credit cards can be powerful tools for building credit, earning rewards, and managing cash flow (when used wisely). However, not every card on the market is designed with the consumer in mind. In fact, some cards are structured in ways that can quietly drain your finances, charge excessive fees, or provide very little real benefit in return.

With so many options available today, it’s easy to fall into the trap of choosing a card that looks flashy but ends up being a financial burden. From high interest rates to deceptive perks, here are five credit cards that most people are better off leaving out of their wallets.

1. Store-Branded Credit Cards With Sky-High APRs

It’s tempting to say “yes” when the cashier offers you a 10% discount for opening a store credit card. But many of these cards come with interest rates that soar well above the national average—sometimes over 28%.

What’s worse is that the rewards you earn are usually only good at that specific store, meaning you’re locked into spending more just to redeem the points. These cards also tend to have low credit limits, which can hurt your credit utilization ratio and negatively impact your credit score. Unless you shop at a particular retailer often and pay your balance in full every month, store credit cards often do more harm than good.

2. Cards With Annual Fees That Don’t Justify the Cost

There are premium cards that offer real value—think travel credits, lounge access, or generous points programs. But many cards charge an annual fee without offering nearly enough in return. If you’re not actively using all of a card’s benefits, you might be paying $95 to $300+ a year for rewards you’re not even using. These cards are particularly bad for people who don’t travel often or who primarily use credit cards for basic purchases.

Before you accept a card with an annual fee, run the numbers. If the perks don’t clearly outweigh the cost, it’s not worth it, no matter how fancy the card looks.

3. Secured Credit Cards With Excessive Fees

Secured credit cards can be a great way to rebuild credit, but some issuers take advantage of vulnerable consumers. These are the cards that charge a fee just to apply, hit you with a monthly maintenance fee, and offer a laughably low credit limit even after a large deposit. In the worst cases, your deposit doesn’t even earn interest, and you might not get it back if the company folds or imposes questionable rules about account closure.

If you need a secured card, look for one with no annual fee, no application fee, and one that reports to all three credit bureaus. There are good options out there, but you’ll need to read the fine print carefully.
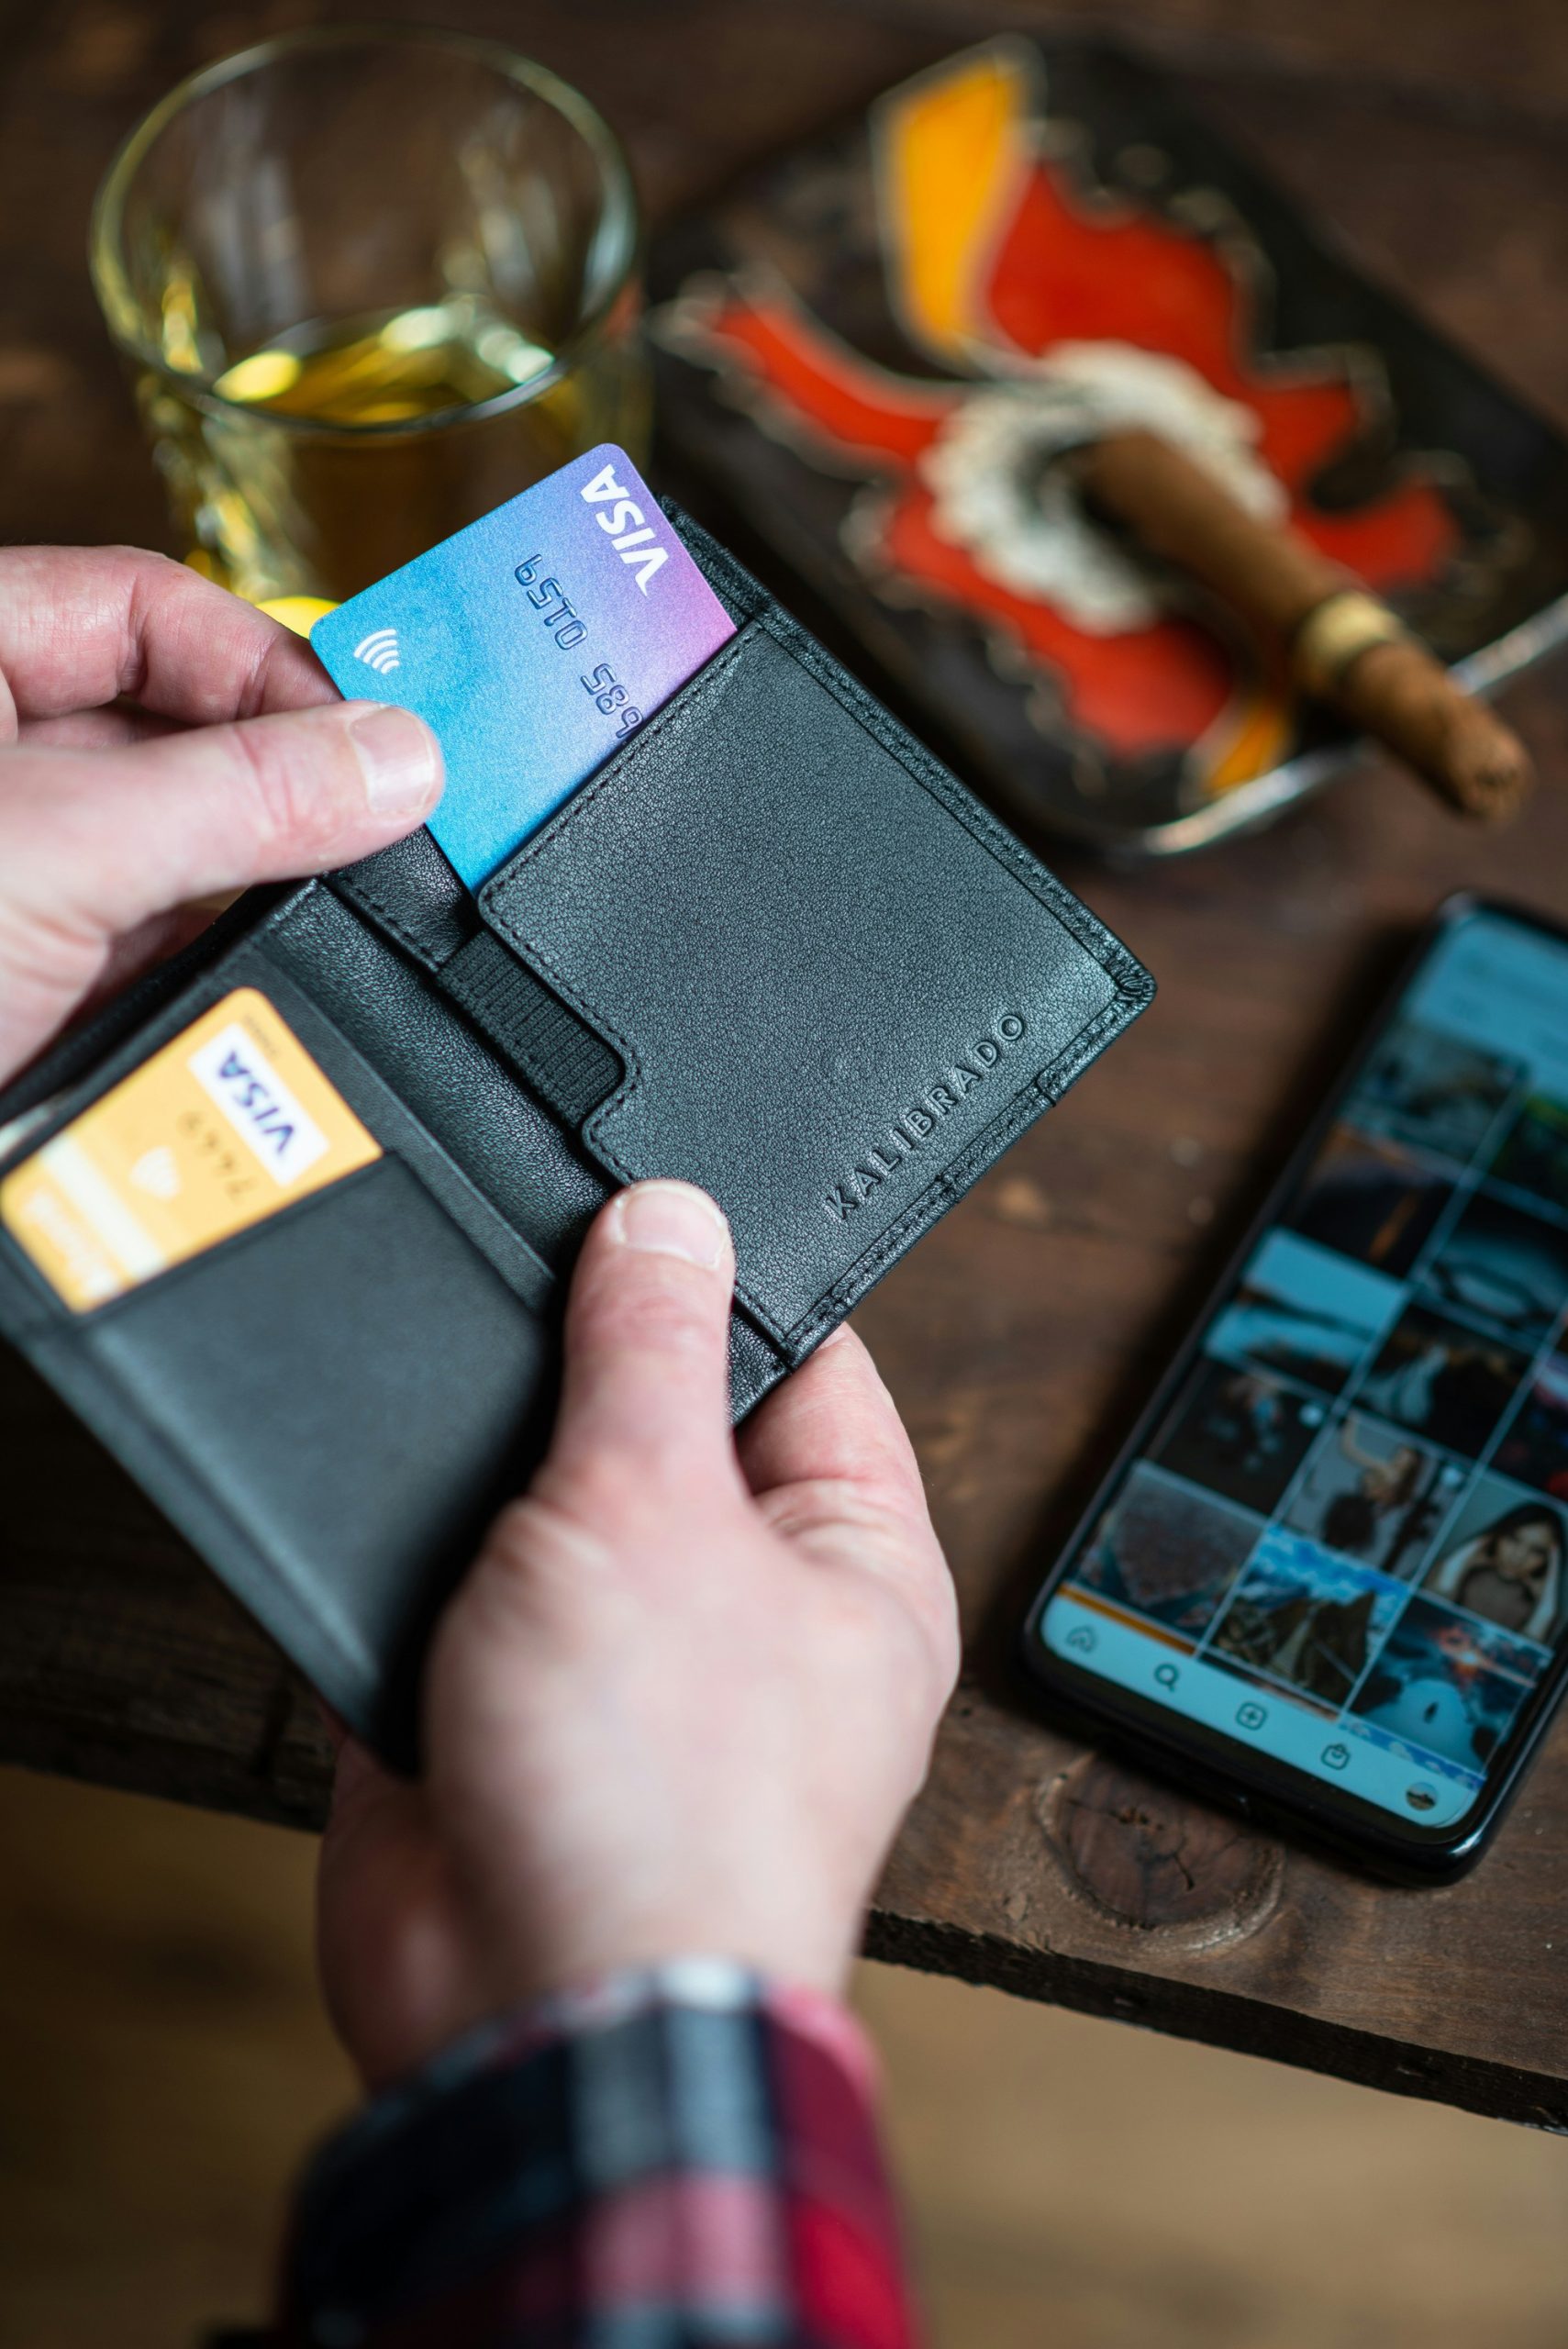
Image by Emil Kalibradov of Unsplash

4. Cards That Market to Poor Credit But Offer No Real Help

Some cards are marketed specifically to people with bad credit, offering “easy approval” with minimal requirements. The problem? They usually come with incredibly high fees, no rewards, and little to no credit-building features. Some may not even report to all three credit bureaus, which defeats the entire purpose of using a credit card to rebuild your score. Others may have traps like monthly account service fees, credit limit increases that come with added fees, or steep penalties for minor infractions.

If you’re rebuilding credit, a better path may be a credit-builder loan, a legitimate secured card, or becoming an authorized user on someone else’s account.

5. Prepaid Debit Cards That Masquerade as Credit

While not technically credit cards, prepaid debit cards are often marketed like them, and people assume they’ll help build credit. But they won’t. You’re simply loading your own money onto a card and then paying to use it. Many prepaid cards come with activation fees, monthly fees, reload fees, and transaction fees. You’re paying to use your own money and getting nothing in return—no rewards, no credit history, and no protection.

If budgeting is your goal, a regular debit card or a budgeting app will do more for less. And if building credit is the priority, you’re better off with a secured credit card that reports your activity.

What You Carry Can Shape Your Financial Future

The cards in your wallet should be tools that work for you, not against you. High fees, low limits, and misleading perks might not seem like a big deal at first, but over time, they can quietly erode your finances and limit your credit potential.

If any of these cards sound familiar, it might be time for a wallet audit. Canceling a card with high fees or low utility, especially if it’s not your oldest account, could be a smart step toward financial clarity.

Have you ever regretted signing up for a certain credit card? Which one, and what happened?

Read More:

7 Simple Ways to Eliminate Credit Card Debt Once and For All

Which Is Safer? 8 Things You Didn’t Know About ACH and Credit Cards

Riley Schnepf

Riley is an Arizona native with over nine years of writing experience. From personal finance to travel to digital marketing to pop culture, she’s written about everything under the sun. When she’s not writing, she’s spending her time outside, reading, or cuddling with her two corgis.

Source link

Total
0
Shares
Share 0
Tweet 0
Pin it 0
Roubens Andy King

Previous Article
What the Happiest Couples Do Differently: 7 Secrets to Steal
  • Invest News

What the Happiest Couples Do Differently: 7 Secrets to Steal

  • April 15, 2025
  • Roubens Andy King
Read More
Next Article
6 Things Your Mail Person Knows About You
  • Invest News

6 Things Your Mail Person Knows About You

  • April 15, 2025
  • Roubens Andy King
Read More
You May Also Like
Robert Pattinson Finally Picks His Favorite Meme of Himself, but He Still Has No Idea Why It’s Funny
Read More
  • Invest News

Robert Pattinson Finally Picks His Favorite Meme of Himself, but He Still Has No Idea Why It’s Funny

  • Roubens Andy King
  • September 27, 2026
What Happens If Nobody Claims a Life Insurance Policy?
Read More
  • Invest News

What Happens If Nobody Claims a Life Insurance Policy?

  • Roubens Andy King
  • September 23, 2026
Make money by selling your hair
Read More
  • Invest News

Make money by selling your hair

  • Roubens Andy King
  • September 23, 2026
Fed Breaks Three-Year Pause, Raises Rates a Quarter Point as Inflation Refuses to Cool
Read More
  • Invest News

Fed Breaks Three-Year Pause, Raises Rates a Quarter Point as Inflation Refuses to Cool

  • Roubens Andy King
  • September 17, 2026
Kendall Jenner Denies Dating Cara Delevingne, Then Jokes ‘Never Say Never’
Read More
  • Invest News

Kendall Jenner Denies Dating Cara Delevingne, Then Jokes ‘Never Say Never’

  • Roubens Andy King
  • September 17, 2026
Is ,000 Enough for a Retirement Emergency Fund? Run These 5 Expenses First
Read More
  • Invest News

Is $5,000 Enough for a Retirement Emergency Fund? Run These 5 Expenses First

  • Roubens Andy King
  • September 13, 2026
A Benefits Administrator Managed Health Funds for Three School Districts. Police Say 0,695 Was Transferred Without Permission
Read More
  • Invest News

A Benefits Administrator Managed Health Funds for Three School Districts. Police Say $810,695 Was Transferred Without Permission

  • Roubens Andy King
  • September 9, 2026
Looking for a Work-From-Home Side Hustle? The Truth About Viral Pen and Craft Assembly Jobs
Read More
  • Invest News

Looking for a Work-From-Home Side Hustle? The Truth About Viral Pen and Craft Assembly Jobs

  • Roubens Andy King
  • September 9, 2026

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Recent Posts

  • 22 साल का करोड़पति 💰 | Transport and Travels Business EXPOSED | Marwari Business Success Story ✅
  • Robert Pattinson Finally Picks His Favorite Meme of Himself, but He Still Has No Idea Why It’s Funny
  • Why Pepsi Ended Up Owning A Navy🤯 #pepsi #navy #finance #history
  • AS 13 Revision | Investment Accounts | Concepts + IMP Questions | CA Inter | CA Aakash Kandoi
  • Federal Reserve Board – Federal Reserve Board announces approval of application by Peoples Bancorp Inc.
Featured Posts
  • 22 साल का करोड़पति 💰 | Transport and Travels Business EXPOSED | Marwari Business Success Story ✅ 1
    22 साल का करोड़पति 💰 | Transport and Travels Business EXPOSED | Marwari Business Success Story ✅
    • September 27, 2026
  • Robert Pattinson Finally Picks His Favorite Meme of Himself, but He Still Has No Idea Why It’s Funny 2
    Robert Pattinson Finally Picks His Favorite Meme of Himself, but He Still Has No Idea Why It’s Funny
    • September 27, 2026
  • Why Pepsi Ended Up Owning A Navy🤯 #pepsi #navy #finance #history 3
    Why Pepsi Ended Up Owning A Navy🤯 #pepsi #navy #finance #history
    • September 26, 2026
  • AS 13 Revision | Investment Accounts | Concepts + IMP Questions | CA Inter | CA Aakash Kandoi 4
    AS 13 Revision | Investment Accounts | Concepts + IMP Questions | CA Inter | CA Aakash Kandoi
    • September 25, 2026
  • Federal Reserve Board – Federal Reserve Board announces approval of application by Peoples Bancorp Inc. 5
    Federal Reserve Board – Federal Reserve Board announces approval of application by Peoples Bancorp Inc.
    • September 25, 2026
Recent Posts
  • Dry Mutton Business Series | Chapter 1 | Episode 6 #drymutton #shortsfeed #daily
    Dry Mutton Business Series | Chapter 1 | Episode 6 #drymutton #shortsfeed #daily
    • September 24, 2026
  • Federal Reserve Board – Federal Reserve Board requests public comment on two proposals related to establishing a regulatory framework for Board-supervised payment stablecoin issuers under the GENIUS Act
    Federal Reserve Board – Federal Reserve Board requests public comment on two proposals related to establishing a regulatory framework for Board-supervised payment stablecoin issuers under the GENIUS Act
    • September 24, 2026
  • Federal Reserve Board – Federal Reserve Board issues enforcement action with former employee of Sandy Spring Bank
    Federal Reserve Board – Federal Reserve Board issues enforcement action with former employee of Sandy Spring Bank
    • September 24, 2026
Categories
  • Business (2,057)
  • Crypto (2,023)
  • Economy (345)
  • Finance Expert (1,687)
  • Forex (2,016)
  • Invest News (2,519)
  • Investing (2,040)
  • Tech (2,056)
  • Trading (2,024)
  • Uncategorized (2)
  • Videos (1,172)

Subscribe

Subscribe now to our newsletter

Money Visa
  • Privacy Policy
  • DMCA
  • Terms of Use
Money & Invest Advices

Input your search keywords and press Enter.